Strategic Marketing Intelligence — Analysis Series. Prepared by Jim Ikpehai, Mediology Nigeria. Published April 2026.
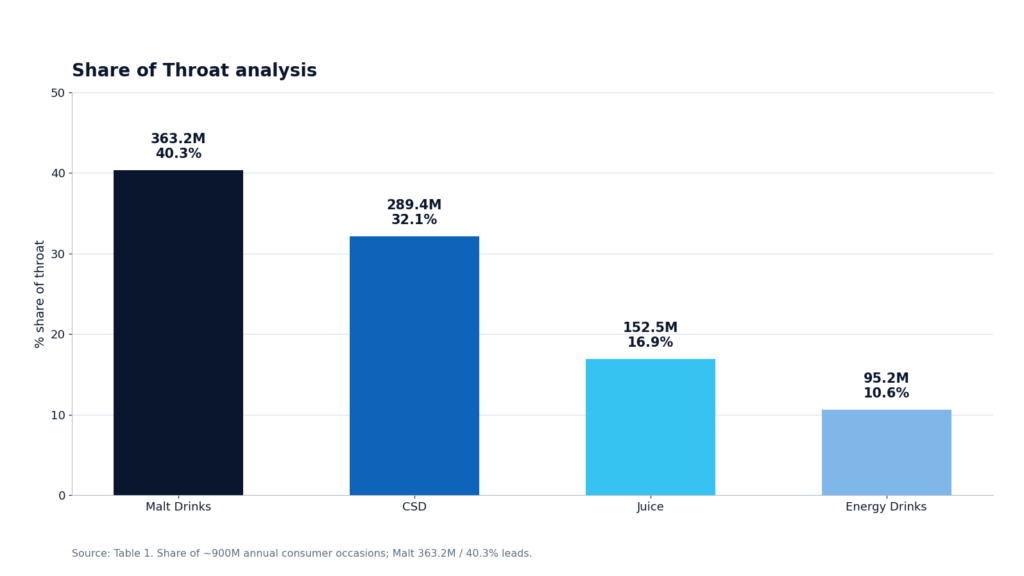
Nigeria’s cold beverage market spans roughly 900 million consumer occasions a year across four categories — malt drinks, CSD, juice and energy drinks. Malt is the social default at 40.3% share of throat (363.2 million consumers, 75.2% penetration), CSD holds a strong second at 32.1%, and juice (16.9%) and energy drinks (10.6%) are the emerging growth categories. One market stands above all the rest: Lagos, with a Priority Score of 6.47, is the only Tier 1 market in the country.
This analysis applies the BCG Matrix, GE-McKinsey Matrix, Category Development Index and Share of Throat frameworks to direct market entry and expansion — across Nigeria’s 36 states and the FCT, six regions and four categories.
1. Executive summary
A 900-million-occasion market with one undisputed capital.
This Nigeria cold beverage market analysis covers roughly 900 million consumer occasions a year across four categories. This analysis applies the BCG Matrix, GE-McKinsey Matrix, Category Development Index and Share of Throat frameworks to direct market entry and expansion.
| Stat | Value |
|---|---|
| Total addressable consumer occasions annually | 900M |
| Malt drinks — dominant share of throat | 40.3% |
| Lagos priority score — the only Tier 1 market | 6.47 |
Table 1 · National market overview by category
| Category | Total consumers | Market share | Avg. penetration |
|---|---|---|---|
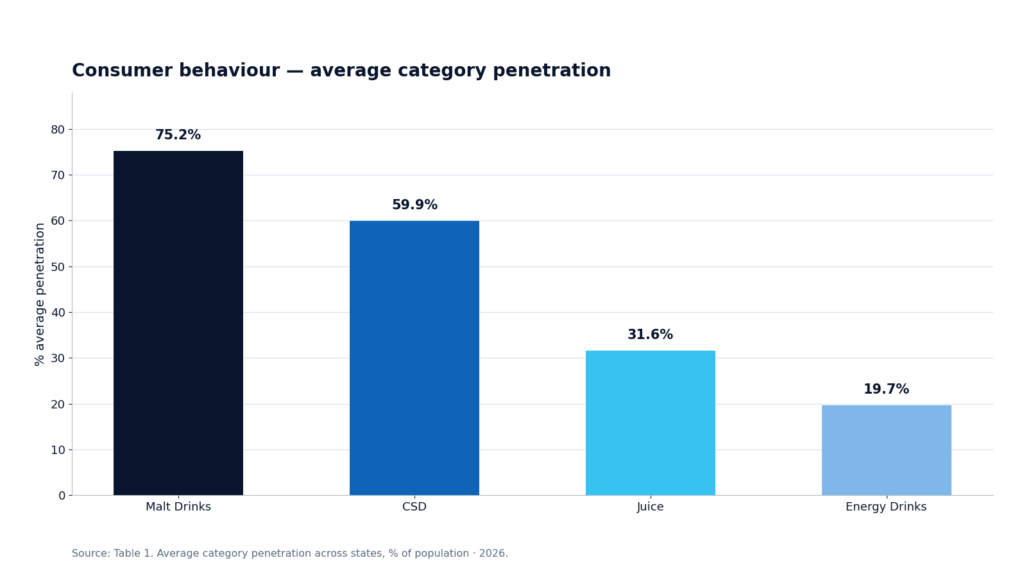
| Malt Drinks | 363,164,498 | 40.3% | 75.2% |
| CSD | 289,363,348 | 32.1% | 59.9% |
| Juice | 152,547,026 | 16.9% | 31.6% |
| Energy Drinks | 95,220,072 | 10.6% | 19.7% |
Strategic imperatives
Lagos is the undisputed priority market — GDP per capita of ₦3.68M, 87.4% internet penetration, 35.3M consumer occasions. Malt leads the portfolio as a Star; Energy Drinks are the high-growth Question Mark. The North West and South West carry the largest volumes, while Osun shows exceptional category development — CDI above 140 across all segments.
The bottom line
Regional disparities are economic at their root: states with higher GDP per capita and internet penetration show elevated penetration across all categories. Follow the economics — concentrate investment where attractiveness and development already meet.
2. Nigeria cold beverage market overview & share of throat
Malt drinks are Nigeria’s social default
Share of Throat reveals the competitive structure: malt commands 40.3% on deep cultural roots, CSD holds a strong second at 32.1%, while juice and energy drinks are the emerging growth categories.
Why malt wins
Cultural acceptance as a social beverage, positioning as a premium non-alcoholic alternative, and established distribution networks. The category enjoys strong brand equity among leading players and deep penetration into both urban and rural markets.
Volume lives in the North West; intensity lives in the South East
The North West leads absolute occasions (109.8M) on its 61.6M population base; the South West follows at 95.7M; the South East shows the highest per-capita consumption intensity.
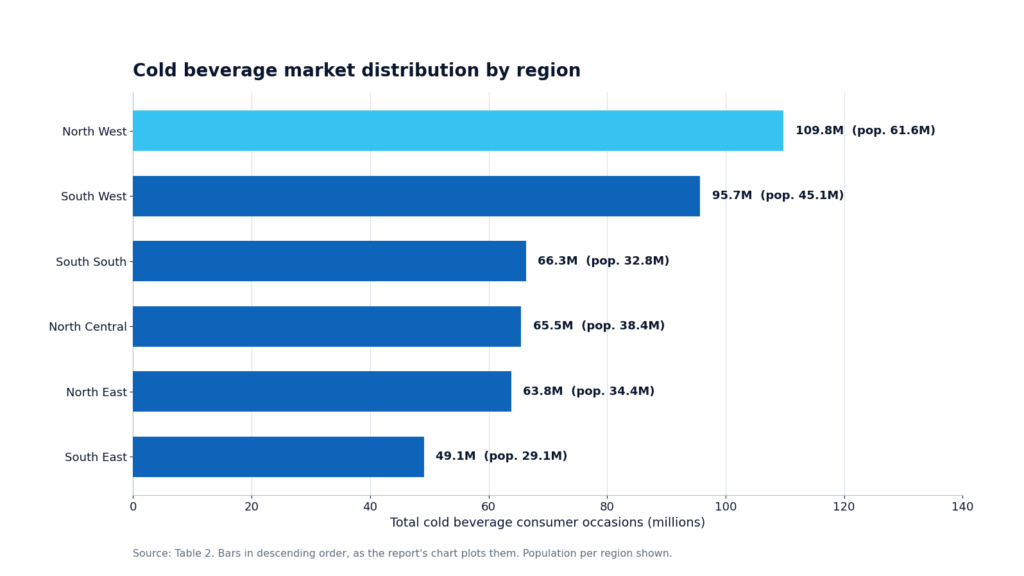
Table 2 · Regional market summary
| Region | Population | Total consumers | Malt | CSD | Juice | Energy |
|---|---|---|---|---|---|---|
| North Central | 38.4M | 65.5M | 39.9% | 31.8% | 17.7% | 10.5% |
| North East | 34.4M | 63.8M | 41.8% | 32.0% | 15.1% | 11.2% |
| North West | 61.6M | 109.8M | 39.2% | 34.0% | 17.0% | 9.8% |
| South East | 29.1M | 49.1M | 39.5% | 31.6% | 19.1% | 9.8% |
| South South | 32.8M | 66.3M | 41.8% | 31.6% | 16.5% | 10.1% |
| South West | 45.1M | 95.7M | 40.4% | 31.0% | 16.9% | 11.8% |
North West — Largest absolute market; CSD preference highest at 34%.
South East — Highest juice share (19.1%) — health-conscious behaviour.
South West — Balanced portfolio; highest energy share (11.8%).
North East — Strong malt preference (41.8%) on cultural patterns.
3. BCG matrix — portfolio analysis
One Star, one Cash Cow, two decisions to make
The BCG Matrix positions each category on market growth and relative share — clarifying where to invest, where to milk, and where to decide.
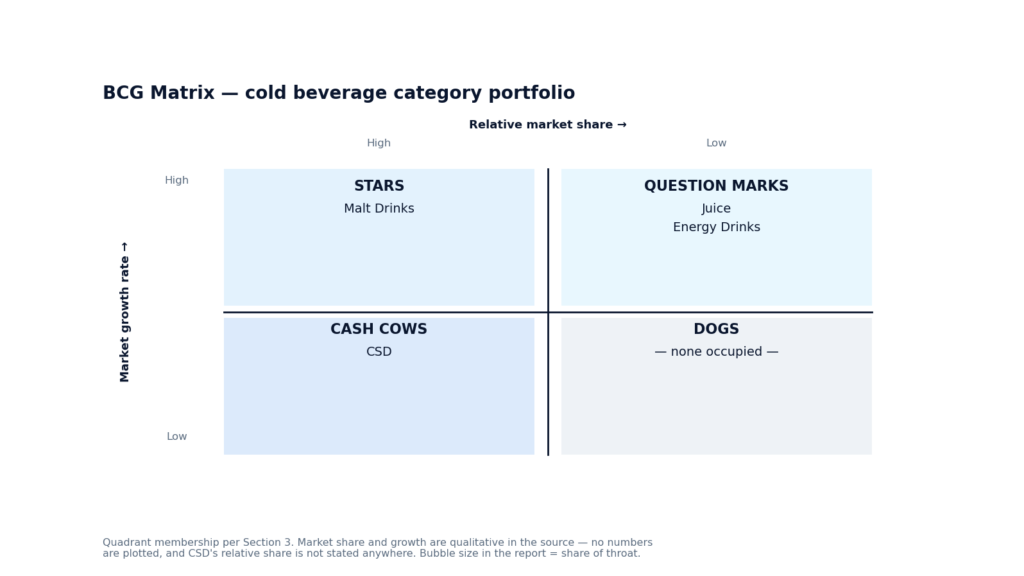
Stars · Malt Drinks
Highest share (index 100) with a strong growth trajectory. Generates significant cash while requiring continued investment — premiumize and expand occasions.
Cash Cows · CSD
Mature growth, stable cash flows, minimal investment needs. Strategy: efficiency and selective innovation to extend the lifecycle.
Question Marks · Juice & Energy
Juice (42 relative share) and Energy (26.2) carry high growth potential at low share — invest to build, or redirect resources.
4. GE-McKinsey matrix — state positioning
Thirty-seven markets, one Invest & Grow occupant
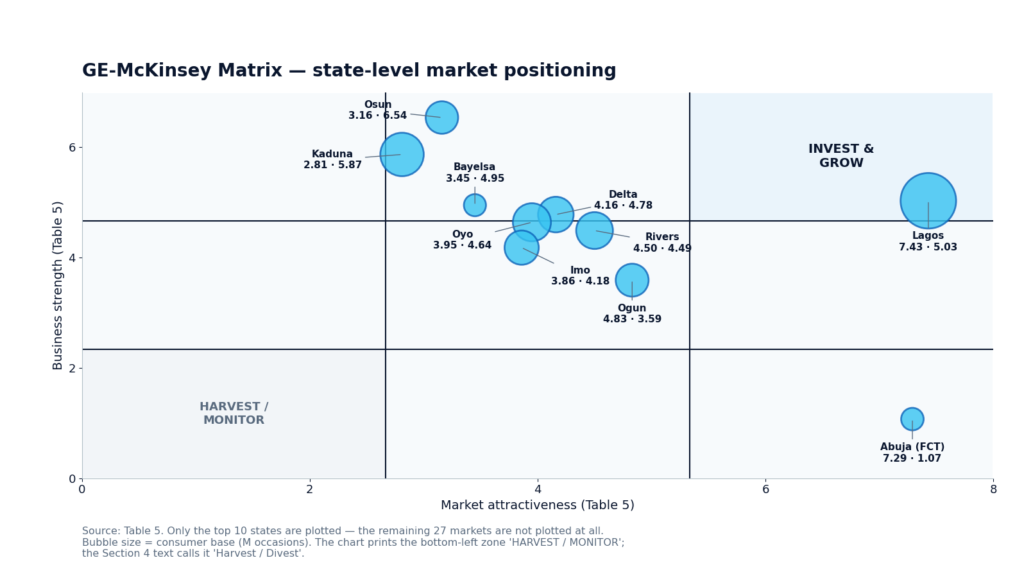
The nine-cell matrix weighs market attractiveness — population (20%), GDP per capita (25%), internet (15%), banking access (10%), population growth (15%), middle class (15%) — against business strength from market size and category penetration.
Invest / Grow
Lagos alone — attractiveness 7.43, strength 5.03: prosperity, connectivity and 35.3M occasions in one market.
Selectivity / Earnings
Abuja FCT (high attractiveness, low strength), Osun (high strength, moderate attractiveness) and Rivers — selective investment strategies.
Harvest / Divest
Several northern states with lower economic indicators and smaller markets — defend share at low cost.
5. Category Development Index (CDI)
Osun out-develops every state — Abuja under-delivers
CDI measures category development per state against the national average (100). The spread between peaks and troughs maps where demand is proven and where it is still latent.
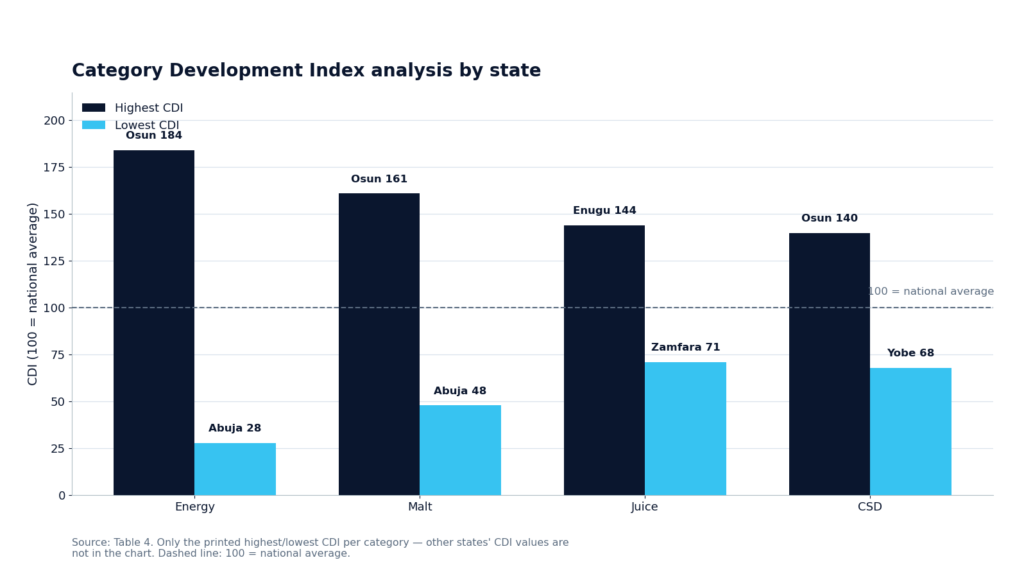
Table 4 · CDI summary by category
| Category | Highest CDI | Lowest CDI | Strategic implication |
|---|---|---|---|
| Malt Drinks | Osun (161) | Abuja (48) | Rural markets show higher malt affinity |
| CSD | Osun (140) | Yobe (68) | South West leads CSD consumption |
| Juice | Enugu (144) | Zamfara (71) | South East shows health consciousness |
| Energy Drinks | Osun (184) | Abuja (28) | High variance indicates opportunity |
CDI above 120
Market defense, premiumization and loyalty programmes.
CDI 80–120
Invest in distribution expansion and consumer education.
CDI below 80
Evaluate potential — selective entry or partnerships.
6. Market Prioritization Index
Lagos is Tier 1 — alone
The Market Prioritization Index blends market attractiveness (60%) with business strength (40%) into a single investment ranking.
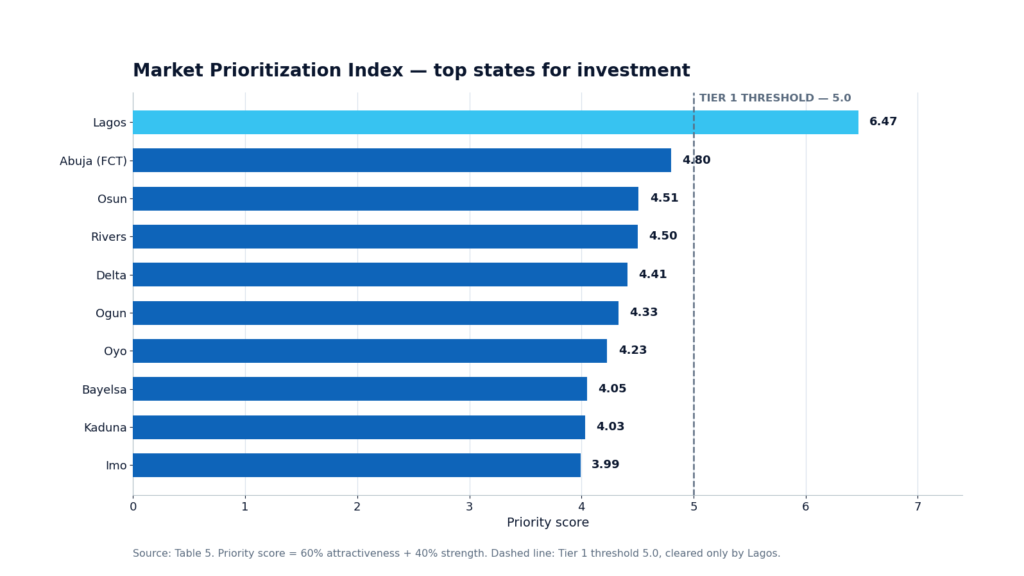
Table 5 · Top 10 priority states for investment
| Rank | State | Region | Priority score | Attractiveness | Strength | Consumer base |
|---|---|---|---|---|---|---|
| 1 | Lagos | South West | 6.47 | 7.43 | 5.03 | 35.3M |
| 2 | Abuja (FCT) | North Central | 4.80 | 7.29 | 1.07 | 5.8M |
| 3 | Osun | South West | 4.51 | 3.16 | 6.54 | 12.1M |
| 4 | Rivers | South South | 4.50 | 4.50 | 4.49 | 15.5M |
| 5 | Delta | South South | 4.41 | 4.16 | 4.78 | 14.5M |
| 6 | Ogun | South West | 4.33 | 4.83 | 3.59 | 12.4M |
| 7 | Oyo | South West | 4.23 | 3.95 | 4.64 | 16.6M |
| 8 | Bayelsa | South South | 4.05 | 3.45 | 4.95 | 5.6M |
| 9 | Kaduna | North West | 4.03 | 2.81 | 5.87 | 21.6M |
| 10 | Imo | South East | 3.99 | 3.86 | 4.18 | 13.4M |
Investment tiers
Tier 1 (score above 5.0): Lagos stands alone — maximum investment in distribution, marketing and innovation. Tier 2 (4.0–5.0): Abuja FCT, Osun, Rivers, Delta, Ogun, Oyo, Bayelsa and Kaduna — focused growth investment. Tier 3 (below 4.0): efficient coverage and monitoring.
7. Consumer behaviour & cultural insights
Every category answers a different Nigerian occasion
Consumption drivers tie category penetration to economic development, digital connectivity and culture — each category owns a distinct occasion.
Malt — celebration
Embedded in social culture: celebrations, religious gatherings, hospitality. Transcends class — 70%+ penetration in most states.
CSD — youthful refreshment
Younger, urban audiences on strong brand recognition and distribution — facing health-consciousness headwinds.
Juice — the healthy choice
Correlates with education and health awareness; strongest in the South East and urban centres.
Energy — the hustle
Working professionals, students, urban youth — the highest growth potential, concentrated in economically active populations.
Behavioural shifts reshaping the market
Health consciousness drives juice and low-sugar interest · Urbanization expands premium addressable markets · Digital influence links internet penetration to global beverage trends · Convenience seeking fuels single-serve packaging demand.
8. Strategic recommendations by segment
Defend malt, optimize CSD, educate juice, build energy
Four categories, four distinct playbooks — matched to each category’s portfolio position and development profile.
Malt · Defend & premiumize
Hold traditional-trade dominance; introduce premium variants for trading-up; occasion marketing around celebrations; push rural penetration where CDI peaks.
CSD · Optimize & innovate
Focus core high-velocity SKUs; reduced-sugar variants; cross-category leverage of distribution; youth targeting via digital and event sponsorships.
Juice · Educate & expand
Nutrition education; prioritize South East and high-CDI urban markets; affordable pack sizes for mass reach; natural and fresh positioning.
Energy · Invest & build
Prioritize CDI-100+ growth markets; target professionals and students; sports and music sponsorships; functional variants — sugar-free, vitamin-enriched.
Table 6 · Regional strategic priorities
| Region | Strategic priority | Key actions |
|---|---|---|
| South West | Growth & premiumization | Expand distribution, introduce premium SKUs |
| North West | Volume optimization | Strengthen traditional trade, optimize logistics |
| South South | Market development | Build brand presence, expand cooler placement |
| South East | Health positioning | Promote juice and low-sugar variants |
| North Central | Selective investment | Focus on Abuja and key urban centres |
| North East | Market maintenance | Defend core distribution, monitor security |
9. Summary of findings & conclusion
Prioritize the right markets, back the growth categories
Four frameworks converge on one story: a 900-million-occasion market where malt and CSD form the core, juice and energy carry the growth, and economics decide the map.
Market structure
Malt (40.3%) and CSD (32.1%) form the core; juice (16.9%) and energy (10.6%) are the growth opportunities.
Portfolio positioning
Malt is the Star to fund, CSD the Cash Cow to optimize, juice and energy the Question Marks to decide on.
Geographic priorities
Lagos leads (6.47), with Abuja FCT, Osun, Rivers and Delta as Tier 2 — the South West is the most attractive region overall.
Category development
Osun is the most developed market across categories; Abuja’s low CDI despite its economics signals untapped potential.
Strategic conclusions
Invest in Lagos — no comparable scale and attractiveness · Defend malt leadership — the portfolio’s foundation · Grow energy drinks — the highest growth potential · Target the South West — the best combination of size, development and growth · Monitor health trends — consciousness will reshape the market.
Brands that prioritize the right markets, invest in growth categories and adapt to cultural nuance will capture disproportionate value in this dynamic market.
About the author
Jim Ikpehai Managing Consultant · Mediology Nigeria Limited, Lagos
Results-driven marketing communications strategist with over 15 years of experience in brand building, brand development and management. A trusted consultant to global and local brands including Samsung, Reliance HMO, Polo Swarovski, FBN Holdings, M-KOPA, Honda Nigeria, Daraju Industries and De Trans — delivering 360° marketing, communication strategies, media planning and buying, digital marketing, SEO, content strategy and marketing analytics.
Education
- Ph.D. Economics — Sustainable Growth & Development (in view), University of Lagos
- M.Sc. Economics — Growth & Development, Monetary & Energy Economics, University of Lagos
- B.Sc. Economics — University of Lagos
- Level 6 Diploma in Strategic Marketing — Chartered Institute of Marketing (CIM), UK
Career highlights
- Managing Consultant — Mediology Nigeria Ltd (2025–present)
- Director of Planning & Strategy — Solid Media Nigeria (2022–2025)
- Head, Media Planning & Strategy — HoiSales Nigeria (2020–2022)
- Head, Planning / Insight & Analytics — All Seasons Zenith (Publicis Groupe), Lagos (2014–2020)
- Senior Manager, Research / Planning & Innovation — All Seasons Zenith (Publicis), 2013–2014
- Manager, Data Analytics & Innovation — MediaCom (WPP), 2011–2013
Memberships & recognition
- Juror, Young Lions National Competition (Cannes Lions pathway) — 2024 & 2025
- Juror, Pitcher Awards — 2024
- Panelist, Social Media Week Lagos — 2019
- Fellow, Institute of Management Consultants of Nigeria (FIMC)
- Associate Member, Advertising Practitioners Council of Nigeria (APCON)
- Member, Chartered Institute of Marketing (CIM), UK
15+ years in marketing communications · WPP · Publicis global network experience · ALAT launch team — Nigeria’s first digital bank · 2× Young Lions juror · 2024 & 2025
jim@mediologyng.com · +234 703 630 0230 · linkedin.com/in/jimikpehai75564295
See our Services page for the six integrated disciplines behind this approach.
Frequently asked questions
How big is Nigeria’s cold beverage market?
Roughly 900 million consumer occasions a year across four categories: malt drinks lead with 363.2 million consumers at 40.3% share of throat, followed by CSD at 289.4 million (32.1%), juice at 152.5 million (16.9%) and energy drinks at 95.2 million (10.6%).
Which state should a cold beverage brand enter first?
Lagos. It scores 6.47 on the Market Prioritization Index — the only Tier 1 market in the country — with attractiveness of 7.43, strength of 5.03, 35.3 million consumer occasions, GDP per capita of ₦3.68M and 87.4% internet penetration. No other market combines that scale with that attractiveness.
Which category is the best investment?
It depends on the objective: malt is the Star to defend and premiumize — 40.3% share of throat on deep cultural roots; CSD is the Cash Cow to optimize for efficiency and selective innovation; juice and energy drinks are the Question Marks, with energy carrying the highest growth potential.
Where is the biggest growth opportunity?
Energy drinks — the highest growth potential, concentrated among working professionals, students and urban youth — and juice, riding health consciousness, strongest in the South East. Geographically, Osun shows exceptional category development (CDI above 140 across all segments), while Abuja’s low CDI despite its strong economics signals untapped potential.
Where can I get the full report?
The full 14-page Cold Beverage Market Attractiveness Index — Nigeria is available to download below. For a tailored reading of the findings for your business, or a state-level deep dive, contact Mediology Nigeria at info@mediologyng.com or visit 1 Montgomery Road, Yaba, Lagos.
This report was prepared by Jim Ikpehai, Mediology Nigeria — data-driven marketing communications excellence. For the full analysis, including every market ranking and the underlying data, download the complete report below.